Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
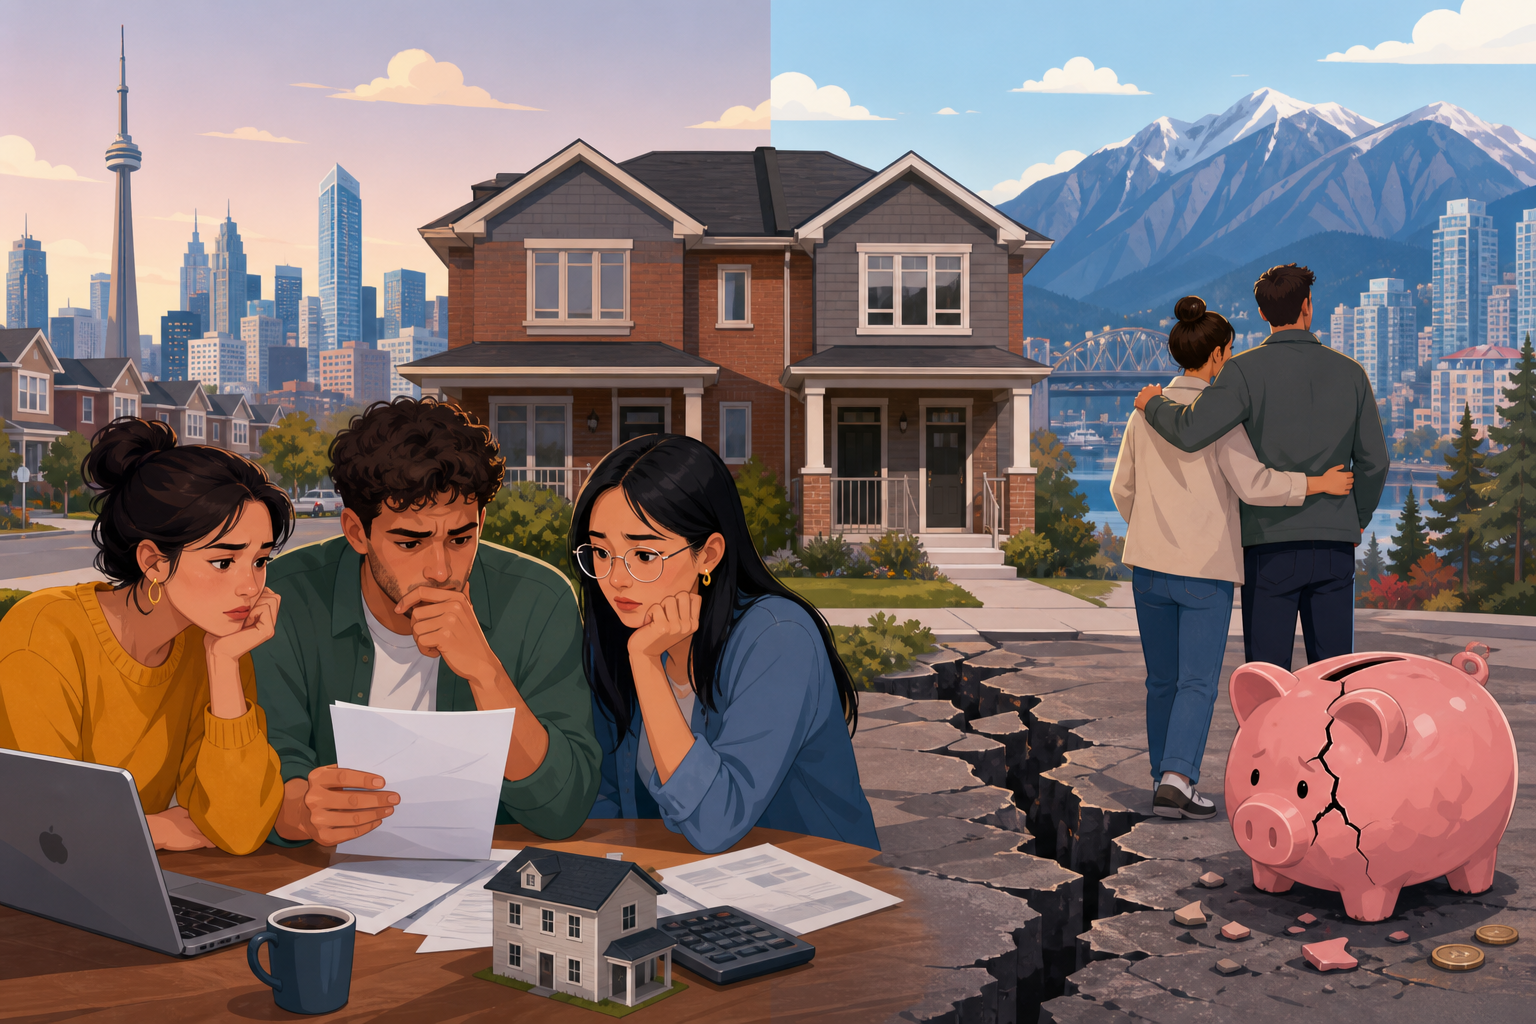
A $620,000 semi-detached in Etobicoke requires income documentation for three people now. Not because the borrowers are polyamorous roommates or launching a commune. Because that's what it takes to pass the federal mortgage stress test when the qualifying rate sits at roughly 7% and the average household can't carry the load alone.
Equifax's September 2026 data confirms what brokers have been seeing for two years: joint mortgages involving three or more borrowers now account for roughly one in three first-time buyer applications in major Ontario and B.C. markets. The national mortgage delinquency rate remains historically manageable, but the two provinces where housing costs the most are starting to separate from the pack. Ontario's 90-day delinquency rate climbed 52 percent year-over-year through late 2025 and into 2026. B.C. posted a 36 percent increase year-over-year.
The arithmetic is simple. OSFI's stress test forces borrowers to qualify at their contract rate plus 200 basis points, or 5.25 percent, whichever is higher. A buyer locking in at 4.8 percent today has to prove they can service the loan at 6.8 percent. For a household earning $120,000 gross, that caps borrowing power somewhere south of $450,000 before you add property tax, condo fees, and heating. The average new mortgage balance in Ontario and B.C. now exceeds $500,000.
So buyers add a third name to the application. Sometimes it's a parent who has no intention of living in the property but needs to be on title to satisfy the debt-service ratio. Sometimes it's a genuinely unrelated third professional who will occupy a bedroom and share the monthly nut. The mortgage gets approved. The house gets bought. What happens next is the part nobody stress-tested.
The liability doesn't split cleanly
When one of the three borrowers loses their job or decides to move for work, the remaining two are on the hook for the full monthly payment, and if they can't cover it, all three credit scores take the hit. That's the design. Joint and several liability means the lender can pursue any or all of the co-borrowers for the full debt.
Equifax's data shows mortgage holders in high-cost provinces now carrying elevated balances on non-mortgage credit, cards and lines of credit, to manage monthly cash flow. That's the leading indicator. Before a mortgage goes into formal delinquency, households exhaust the revolving credit. They run the Visa to the limit, tap the HELOC, defer the car payment. By the time the mortgage itself is 90 days past due, the household balance sheet has been eroding for six months or longer.
The "roommate mortgage" works fine when all three incomes remain stable and nobody's life circumstances change. It fails the moment one person's financial position deteriorates or they want out, because selling a jointly owned property requires unanimous consent, and unwinding shared title in a soft market is neither fast nor cheap.
What the national figures hide
The contained national delinquency rate is a statistical artifact. A stable mortgage market in Winnipeg or Halifax offsets the genuine financial distress accumulating in the Golden Horseshoe and the Lower Mainland. The problem is geographically concentrated in the two provinces where home prices never corrected enough to restore traditional lending ratios.
The labour market remains the last line of defense. As long as unemployment stays low, most of these multi-borrower households can scrape together the payment. A recession changes that math instantly. Three-income households have three separate points of failure, and the 2026 mortgage stock is more sensitive to job loss than any cohort in Canadian history.
What gets called financial innovation usually just means we moved the risk somewhere less visible. Joint mortgages let first-time buyers into the market. They also tied the credit health of three or four people together in a structure that only works if nothing goes wrong. The cracks Equifax is documenting in Ontario and B.C. aren't anomalies. They're what happens when affordability gets bad enough that the solution becomes the problem.


Ontario and B.C. First-Time Buyers Are Borrowing in Pairs, and the Cracks Are Starting to Show
A $620,000 semi-detached in Etobicoke requires income documentation for three people now. Not because the borrowers are polyamorous roommates or launching a commune. Because that's what it takes to pass the federal mortgage stress test when the qualifying rate sits at roughly 7% and the average household can't carry the load alone.
Equifax's September 2026 data confirms what brokers have been seeing for two years: joint mortgages involving three or more borrowers now account for roughly one in three first-time buyer applications in major Ontario and B.C. markets. The national mortgage delinquency rate remains historically manageable, but the two provinces where housing costs the most are starting to separate from the pack. Ontario's 90-day delinquency rate climbed 52 percent year-over-year through late 2025 and into 2026. B.C. posted a 36 percent increase year-over-year.
The arithmetic is simple. OSFI's stress test forces borrowers to qualify at their contract rate plus 200 basis points, or 5.25 percent, whichever is higher. A buyer locking in at 4.8 percent today has to prove they can service the loan at 6.8 percent. For a household earning $120,000 gross, that caps borrowing power somewhere south of $450,000 before you add property tax, condo fees, and heating. The average new mortgage balance in Ontario and B.C. now exceeds $500,000.
So buyers add a third name to the application. Sometimes it's a parent who has no intention of living in the property but needs to be on title to satisfy the debt-service ratio. Sometimes it's a genuinely unrelated third professional who will occupy a bedroom and share the monthly nut. The mortgage gets approved. The house gets bought. What happens next is the part nobody stress-tested.
The liability doesn't split cleanly
When one of the three borrowers loses their job or decides to move for work, the remaining two are on the hook for the full monthly payment, and if they can't cover it, all three credit scores take the hit. That's the design. Joint and several liability means the lender can pursue any or all of the co-borrowers for the full debt.
Equifax's data shows mortgage holders in high-cost provinces now carrying elevated balances on non-mortgage credit, cards and lines of credit, to manage monthly cash flow. That's the leading indicator. Before a mortgage goes into formal delinquency, households exhaust the revolving credit. They run the Visa to the limit, tap the HELOC, defer the car payment. By the time the mortgage itself is 90 days past due, the household balance sheet has been eroding for six months or longer.
The "roommate mortgage" works fine when all three incomes remain stable and nobody's life circumstances change. It fails the moment one person's financial position deteriorates or they want out, because selling a jointly owned property requires unanimous consent, and unwinding shared title in a soft market is neither fast nor cheap.
What the national figures hide
The contained national delinquency rate is a statistical artifact. A stable mortgage market in Winnipeg or Halifax offsets the genuine financial distress accumulating in the Golden Horseshoe and the Lower Mainland. The problem is geographically concentrated in the two provinces where home prices never corrected enough to restore traditional lending ratios.
The labour market remains the last line of defense. As long as unemployment stays low, most of these multi-borrower households can scrape together the payment. A recession changes that math instantly. Three-income households have three separate points of failure, and the 2026 mortgage stock is more sensitive to job loss than any cohort in Canadian history.
What gets called financial innovation usually just means we moved the risk somewhere less visible. Joint mortgages let first-time buyers into the market. They also tied the credit health of three or four people together in a structure that only works if nothing goes wrong. The cracks Equifax is documenting in Ontario and B.C. aren't anomalies. They're what happens when affordability gets bad enough that the solution becomes the problem.
Sources
Read Next
The OAS Clawback Is 15 Cents Per Dollar, Not 30 or 50
7 streaming services worth paying for in Canada, plus the credit cards that cut your bill
Why Paying Off Your Mortgage First Can Cost You More Than the Interest Rate
Your Emergency Fund Offset Account: Closing a $1,770 Annual Interest Gap